Measure your portfolio's currency exposure
Break a portfolio down by underlying currency and estimate the impact of a move in each exchange rate on its home-currency value.
How much of my portfolio depends on foreign exchange rates?
Currency exposure groups holdings by the currency of their underlying assets, not their listing. A 10% move in a currency changes portfolio value by roughly 10% × that currency's weight, unless hedged.
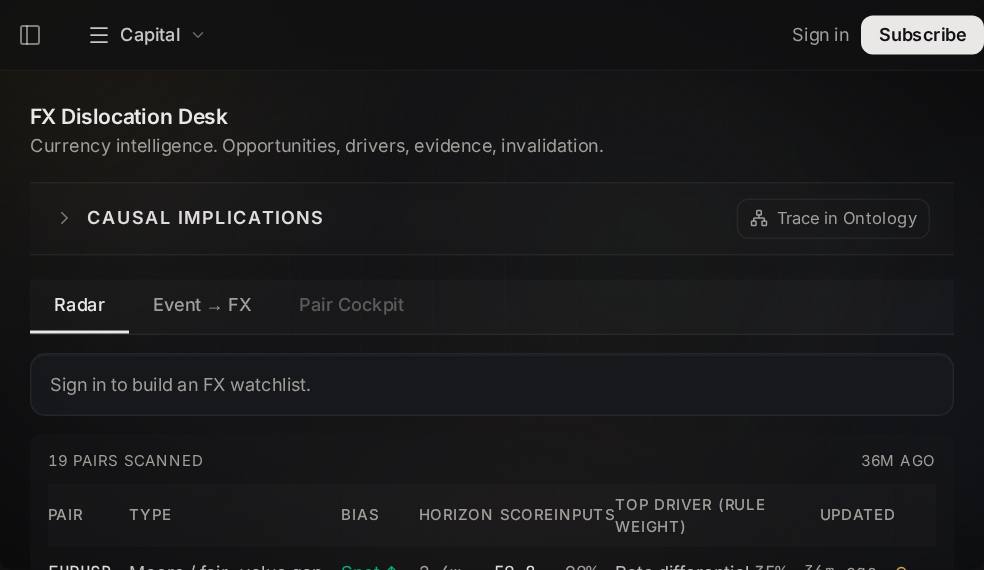
What you see in Market Ontology
The live product, read-only. Your own work opens here after checkout.
Start the job
What opens after checkout
Deterministic FX exposure and scenario analysis, built from the details above and saved to your account in Market Ontology.
- You get
- Deterministic FX exposure and scenario analysis
- Opens in
- Market Ontology
- Built from
- Base currency, exposures, rates, shocks
- Orders
- None; nothing is sent on your behalf